The Property Transfer Tax (Impuesto de Transmisiones Patrimoniales, or ITP) is the main tax payable when buying a second-hand property in Spain. It is therefore important to know which rate applies to the purchase, as this depends on the autonomous community where the property is located.
Each community applies a specific percentage to the cadastral reference value, ranging between 6% and 13%. Reduced rates and other tax reliefs are available in certain circumstances. Here is how much Property Transfer Tax is paid in each autonomous community.
- How much is Property Transfer Tax?
- ITP rates by autonomous community in 2026
- How much ITP is paid in Andalusia in 2026?
- Aragon ITP 2026
- Asturias ITP 2026
- Balearic Islands ITP 2026
- Canary Islands ITP 2026
- Cantabria ITP 2026
- Castile and León ITP 2026
- Castile-La Mancha ITP 2026
- Catalonia ITP 2026
- Extremadura ITP 2026
- Galicia ITP 2026: main home and tax relief
- Property Transfer Tax in Madrid 2026
- Murcia ITP 2026
- Navarre ITP 2026
- ITP in La Rioja in 2026
- Valencian Community ITP 2026
- Basque Country ITP 2026
- How to qualify for reduced ITP
- Where is ITP lowest?
How much is Property Transfer Tax?
Knowing how to calculate ITP and how much is payable in 2026 is essential for working out the real cost of buying a home.
The first thing to bear in mind is that ITP is managed by the autonomous communities, so the location of the property matters a great deal. Although there is a national framework and default rates that apply if a community has not introduced different rules, all communities use their powers to set their own ITP tax rates within the legal framework.
The amount is calculated by applying a percentage to the cadastral reference value. Depending on the autonomous community, reduced rates may also be available in certain circumstances, such as for young buyers or those purchasing VPO homes, or publicly protected housing.
ITP rates by autonomous community in 2026
These are the general ITP rates in each autonomous community in 2026:
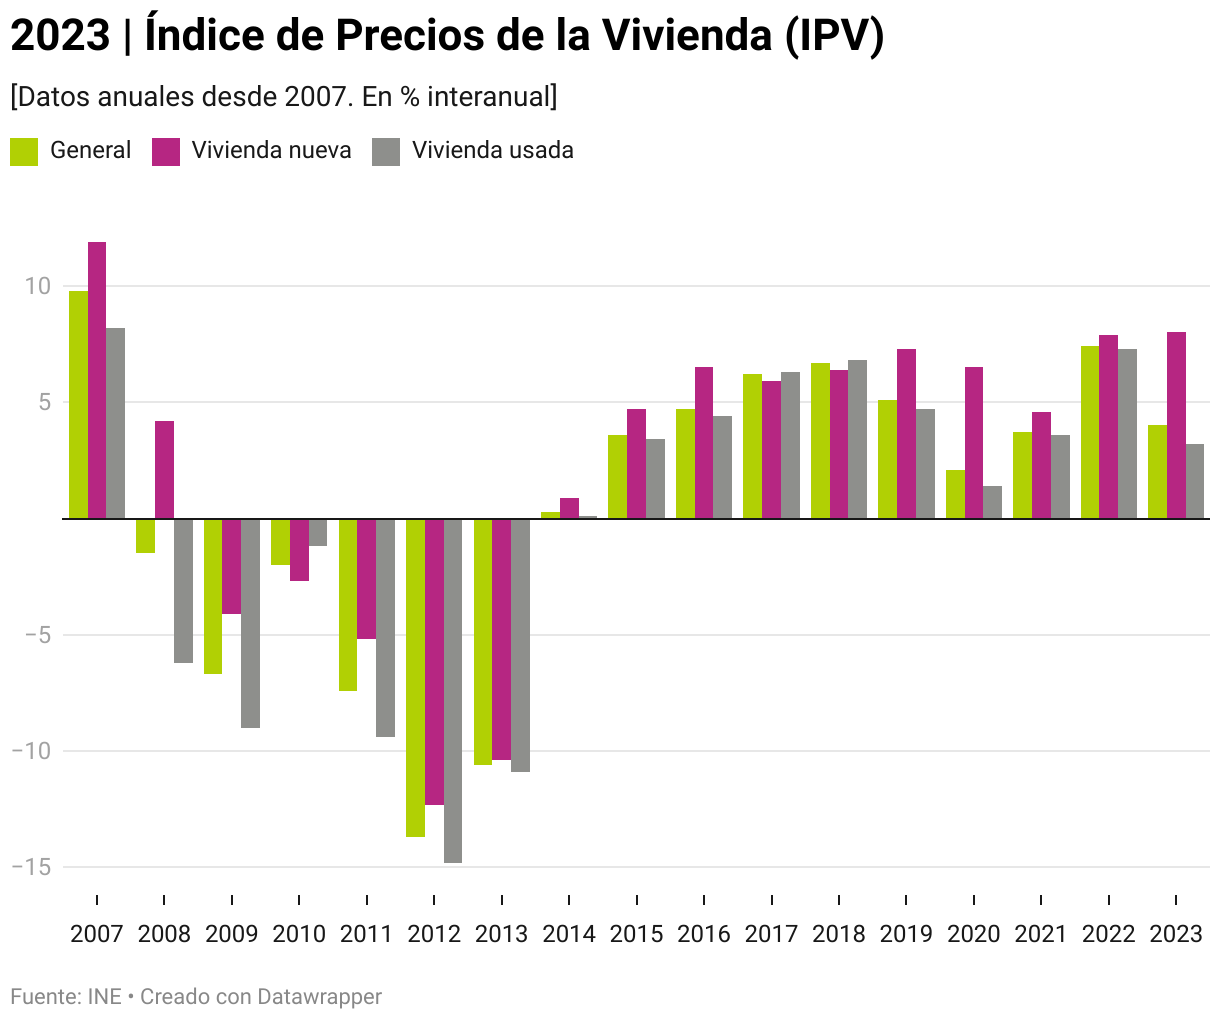
There are exceptions and reduced rates in every autonomous community that may apply in particular cases
How much ITP is paid in Andalusia in 2026?
The general rate for taxable property transfers in Andalusia is 7% for transfers of real estate.
- This falls to 6% when a property is bought as a home, and its actual value does not exceed €150,000.
- It falls to 3.5% for the transfer of properties worth no more than €150,000 that will become the buyer’s main home, provided the buyer is under 35, a victim of domestic violence, a victim of terrorism, or the purchase is in a municipality affected by depopulation.
- The 3.5% rate also applies to properties intended as a main home and worth no more than €250,000 if the buyer is legally recognised as having a disability of 33% or more, or is part of a large family, provided the property will be their main home.
Aragon ITP 2026
ITP in Aragon is calculated according to the property’s value, using the following rates:
Property value up to | Full tax amount | Remaining value up to | Rate |
|---|---|---|---|
€0 | €0 | €400,000 | 8% |
€400,000 | €32,000 | €50,000 | 8.5% |
€450,000 | €36,250 | €50,000 | 9% |
€500,000 | €40,750 | €250,000 | 9.5% |
€750,000 | €64,500 | Thereafter | 10% |
Law 13/2023 of 30 March, on revitalising rural Aragon, also introduced a 60% tax relief for large families buying a main home where the special differentiated tax regime for rural Aragon applies.
- There is also a reduced 1% rate for buying property to start an economic activity, subject to certain requirements, along with a 50% tax relief for large families.
- Buyers under 35, people with a disability of 65% or more, and victims of gender-based violence may also qualify for reductions.
- A dación en pago, where a main home is handed over to settle a mortgage debt, benefits from 100% tax relief.
Asturias ITP 2026
As a general rule, tax on property transfers is calculated by applying the following rates to the taxable base:
Value of the asset or right | Rate |
|---|---|
€0–€300,000 | 8% |
€300,001–€500,000 | 9% |
More than €500,000 | 10% |
The following rates apply to purchases of homes in rural areas at risk of depopulation, as well as main-home purchases by buyers aged up to 35, large families and women who are victims of gender-based violence:
Property value | Rate |
|---|---|
Up to €150,000 | 4% |
More than €150,000 | 6% |
Among other tax reliefs, a 3% rate applies to second and subsequent transfers of homes classified as publicly protected housing by the Principality of Asturias.
Balearic Islands ITP 2026
Property transfers in this autonomous community are subject to the average rate resulting from the following scale, based on the actual value or declared value of the property, if the declared value is higher:
Total value | Full tax amount | Remaining value up to | Applicable rate |
|---|---|---|---|
€0 | €0 | €400,000 | 8% |
€400,000.01 | €32,000 | €200,000 | 9% |
€600,000.01 | €50,000 | €400,000 | 10% |
€1,000,000.01 | €90,000 | €2,000,000 | 12% |
€2,000,000.01 | €210,000 | Thereafter | 13% |
ITP in the Balearic Islands for garage transfers is as follows:
Total value | Full tax amount | Remaining value up to | Applicable rate |
|---|---|---|---|
€0 | €0 | €30,000 | 8% |
€30,000.01 | €2,400 | Thereafter | 9% |
Among other measures, a 4% ITP rate applies to the purchase of a main home where the actual or declared value is €270,151.20 or less, provided the buyer has no other ownership, use or enjoyment rights over another home.
For four years after the purchase, taxpayers cannot acquire another home. The rate falls to 2% in certain circumstances, including for buyers under 36 and people with disabilities.
For buyers under 36, people with disabilities, large families or single-parent families, the rate is 2%, provided the above requirements are met.
Finally, there is a 100% tax relief on the ITP due when a property is bought as the first main home of a young person under 30 or a person with a disability of 33% or more. This applies to tax liabilities arising from 1 January 2024, subject to certain requirements.
Canary Islands ITP 2026
The general rate for taxable property transfers in the Canary Islands is 6.5% for real estate transfers.
This falls to 5% when a property is bought as a main home, provided that, at the time the home is transferred, the taxpayer does not own, hold bare ownership of, or have usufruct rights over another home. If they do, it must be sold within two years.
The taxable base for purchasing the home, including garages and annexes in the same building, cannot exceed €200,000. This is new for 2026. Law 9/2025 of 23 December raised the threshold from €150,000 to the current €200,000, or €300,000 for large families and €400,000 for special-category large families. It entered into force on 1 January 2026, with effect from 1 January 2025.
There is also a reduced 1% rate for main-home purchases by large families, people with disabilities, single-parent families, women who are victims of gender-based violence, and people under 40, previously under 35. In all these cases, income requirements have been updated and eased under Law 9/2025, allowing more taxpayers to qualify for this relief.
Cantabria ITP 2026
The general rate is 9% for real estate transfers.
Different reduced rates apply to homes that will become the taxpayer’s main residence. For instance, the rate is 7% if the assessed value of the home is below €200,000, and 9% if its value is €200,000 or more.
A 4% rate also applies to home transfers involving large or single-parent families, or people with a physical, mental or sensory disability rated at 33% or more but under 65%. If the disability is above 65%, the rate is 3%. The same rate applies to buyers under 36.
Another tax relief is a 5% rate for homes purchased for immediate renovation. This is conditional on the total renovation cost being at least 25% of the home’s purchase price and on the taxpayer submitting the municipal building licence within the established deadline, proving that the renovation cost meets that threshold.
A 3% ITP rate also applies to property transfers where the buyer is a company formed by young entrepreneurs under 36.

Castile and León ITP 2026
The general rate is 8% for property transfers, rising to 10% if the taxable base exceeds €250,000.
The rate falls to 4% for property transfers involving premises that will become the registered office or workplace of companies or professional businesses in certain cases.
This autonomous community also has a reduced 4% rate for homes that will become the buyer’s main residence in the following situations:
- The buyer is part of a large family.
- The buyer, or any member of their household, is recognised as having a disability of 65% or more.
- All buyers are under 36 on the date the tax becomes due.
- The transfer concerns protected housing under regional regulations, or homes classified as publicly protected housing under other legislation.
A rate of 0.01% is also available where the property will become the main home, all buyers are under 36, it is the first home for all buyers, and the property is in a municipality or local entity in Castile and León with fewer than 10,000 residents.
It also applies in places with fewer than 3,000 residents that are less than 30 kilometres from the provincial capital. The home must be worth under €150,000, and the buyers must not exceed a maximum income threshold.
Castile-La Mancha ITP 2026
The general ITP rate in Castile-La Mancha is 9% for real estate transfers. It falls to 6% for the purchase of the taxpayer’s first main home, provided its actual value does not exceed €180,000, and certain requirements are met.
If the home is located in a municipality at risk of depopulation, the reduced rate ranges between 5% and 3%.
There is also a 5% rate for purchases of the taxpayer’s first main home if the buyer is under 36, has a certified disability of 65% or more, or belongs to a large or single-parent family. The home’s value must not exceed €180,000, and certain conditions must be met.
Catalonia ITP 2026
General ITP rates in Catalonia changed substantially on 27 June 2025, following the approval of Decree-Law 5/2025.
Until then, there were two different rates, 10% and 11%, depending on the property’s value. The reform introduced two higher rates of 12% and 13%, increasing the tax burden on high-value property transfers. It also lowered the first threshold from €1,000,000 to €600,000, which in practice increased costs for taxpayers.
As a result, property transfers in 2026 are taxed at the average rate arising from the following scale, based on the property’s actual value:
Total property value | Accumulated full tax amount | Remaining value up to | Applicable rate |
|---|---|---|---|
€0 | €0 | €600,000 | 10% |
€600,000 | €60,000 | €900,000 | 11% |
€900,000 | €93,000 | €1,500,000 | 12% |
€1,500,000 | €165,000 | Thereafter | 13% |
Another key change is the application of a single 20% rate to buyers classed as large property holders, or to those buying entire residential buildings.
A reduced 5% rate still applies to VPO purchases, as well as main-home purchases by large or single-parent families, people with disabilities, buyers under 35, for transfers completed after 27 June 2025, as the upper age limit was previously 32, and victims of gender-based violence. Other requirements must also be met.
As a new measure, transfers of property in a rural municipality intended as a main home have been subject to a 4% rate since 20 August 2025, until 16 July 2029.
If the property is in a rural municipality requiring special attention, the tax rate is 3% during the same period.
Extremadura ITP 2026
As a general rule, tax on property transfers is calculated using the following scale:
Portion of the taxable base | Applicable rate |
|---|---|
€0–€360,000 | 8% |
€360,000–€600,000 | 10% |
More than €600,000 | 11% |
There is also a reduced 7% rate for buying a main home if its actual value does not exceed €200,000. This threshold has applied since 8 April 2025; it was previously set at €122,000. The buyer’s income must also remain below certain limits.
A reduced 6% rate applies to the purchase of property intended for a business or professional activity. There is also a 4% rate for the transfer of VPO homes or the purchase of a main home in rural areas, among other tax reliefs.
Galicia ITP 2026: main home and tax relief
ITP in Galicia is 8% for general real estate transfers, falling to 7% for the purchase of a main home where the household’s assets do not exceed a certain amount. Other reductions can bring the rate down to 3% in certain situations.
Among other measures, a 6% reduced rate applies to home transfers in parroquias, the local parish-level administrative areas considered sparsely populated or rural zones.
A 6% rate also applies to property purchases intended for immediate renovation. This falls to 4% if the property is in a parroquia classed as a sparsely populated or rural zone. Renovation work must be completed within 36 months of the date the tax is paid.
There are also significant tax reliefs and deductions, including a 100% reduction for transfers of rural land or forestry plots.
A 100% deduction is also available for main-home purchases by people with disabilities, large families, buyers under 36, and victims of gender-based violence in rural areas, provided the property is in a parroquia considered a sparsely populated or rural zone.
Property Transfer Tax in Madrid 2026
The general rate in Madrid is 6% for property transfers. It falls to 4% for transfers involving a main home for a large family, provided certain requirements are met.
For main homes, there is a 10% tax relief on the purchase when the actual value is €250,000 or less, and the 4% tax rate does not apply. Meanwhile, the transfer of all or part of one or more homes and their annexes to a company subject to the property-sector adaptation rules of Spain’s General Accounting Plan benefits from a 2% rate.
Murcia ITP 2026
The general ITP rate is 8%. It is 5% for property purchases by entrepreneurs or professionals under 40, or commercial companies wholly and directly owned by people under 40, where the property will be used as their tax residence or workplace.
VPO purchases are subject to a 4% ITP rate, while large families pay 3%. The rate is also 3% for buyers under 40 purchasing a main home, as well as for people with a disability of more than 65%.
Navarre ITP 2026
Property Transfer Tax in the Chartered Community of Navarre is charged at a general rate of 6% of the price for real estate transfers. A reduced rate of 5% of the price applies if the following conditions are met:
- The taxable base does not exceed €180,304. Any amount above this figure is taxed at 6%.
- The household has two or more children.
- Full ownership of the home is acquired.
- The home is used as the household’s main residence.
- No member of the household owns more than a 25% share in another home in the Chartered Community of Navarre. This reduced rate applies to a maximum taxable base of €180,304.
ITP in La Rioja in 2026
La Rioja applies a general 7% rate to real estate transfers. Lower rates apply in certain cases, including 5% for VPO purchases, large families, which may in some cases be reduced to 3%, and people with disabilities of more than 33%.
For purchases of homes that will become the first main residence of buyers under 40 on the date of purchase, the tax rate is 4%. This is a new measure introduced by Law 1/2025 of 28 February on urgent measures for access to housing, which took effect on 3 March 2025. If the home is also in one of the municipalities listed in Annex I of Law 10/2017 of 27 October, the applicable rate is 3%.
Valencian Community ITP 2026
The general ITP rate in the Valencian Community will change midway through 2026, resulting in two situations:
- Until 31 May 2026, the general rate for real estate transfers is 10%.
- From 30 June 2026, the general rate for the sale and purchase of property and real rights falls to 9%.
In both cases, an 11% rate applies where the transferred property is worth more than €1,000,000. This higher rate, which existed before the 2025 reform, remains unchanged. Another change taking effect on 30 June 2026 is a new 4% rate for transfers of land intended for agricultural use.
The ITP reduction in the Valencian Community also remains in place, including a 4% rate for purchasing main homes classified as officially protected housing, where the property’s value does not exceed €180,000.
For home purchases worth more than €180,000, a reduced 4% rate applies to large or single-parent families, people with disabilities, and victims of gender-based violence. If the home is worth less than €180,000, the rate falls to 3%.
There is also a 6% rate for purchases of first homes that will become the main residence of buyers under 35, provided the property does not exceed €180,000 in value.
Basque Country ITP 2026
The general rate for real estate transfers is 7%, and 4% for the transfer of homes, including garage spaces. There are, however, reduced rates and differences between Álava, Gipuzkoa and Bizkaia. In Bizkaia, for example, a reduced 2.5% rate applies to large families buying a main home, subject to certain conditions.
How to qualify for reduced ITP
Qualifying for reduced ITP depends on meeting one of the legal requirements set out in the regulations of the autonomous community where the property is located.
Examples include being below a certain age, buying a VPO home, or having a recognised level of disability. Otherwise, the general rate applies, which, as outlined above, ranges between 6% and 13% depending on the autonomous community.
Where is ITP lowest?
The lowest ITP rates apply in the Community of Madrid, Navarre, Ceuta, Melilla, the Canary Islands, Andalusia, the Basque Country and La Rioja, where rates range between 6% and 7%.
It is worth bearing in mind, however, that different reduced rates and tax reliefs cover particular circumstances and can significantly reduce the amount payable by the buyer.
Stay in the know about living in Spain as a foreigner—get our weekly newsletter for the latest travel, legal, and lifestyle news.